On this page
Get a Kansas City, MO Car Insurance Quote Today
Kansas City drivers deserve clear answers about auto insurance – not confusing jargon or high-pressure sales calls. MissouriAutoInsurance.com helps Kansas City, Missouri drivers compare coverage options online with plain-English guidance from licensed professionals who understand Missouri law and the realities of driving in this metro.
This page is specifically for Kansas City, Missouri (Jackson, Clay, and Platte counties) – not Kansas. Whether you live in the Northland, South KC, Midtown, or anywhere else on the Missouri side, and whether you commute across the state line into Kansas or stay local, we can help you explore your options.
Quote requests through our site are handled by licensed agents at Drivers Insurance Agency, Inc. Submitting your information requests assistance and does not instantly bind coverage or guarantee acceptance.
Ready to start? Get a Kansas City, MO car insurance quote – it only takes a few minutes to enter your details online.
To build an accurate quote, you’ll typically need your driver info, vehicle details, Kansas City garaging address, and driving history. We’ll walk you through every Missouri coverage type in language that actually makes sense, and you can speak with a licensed agent if you want help understanding your options.
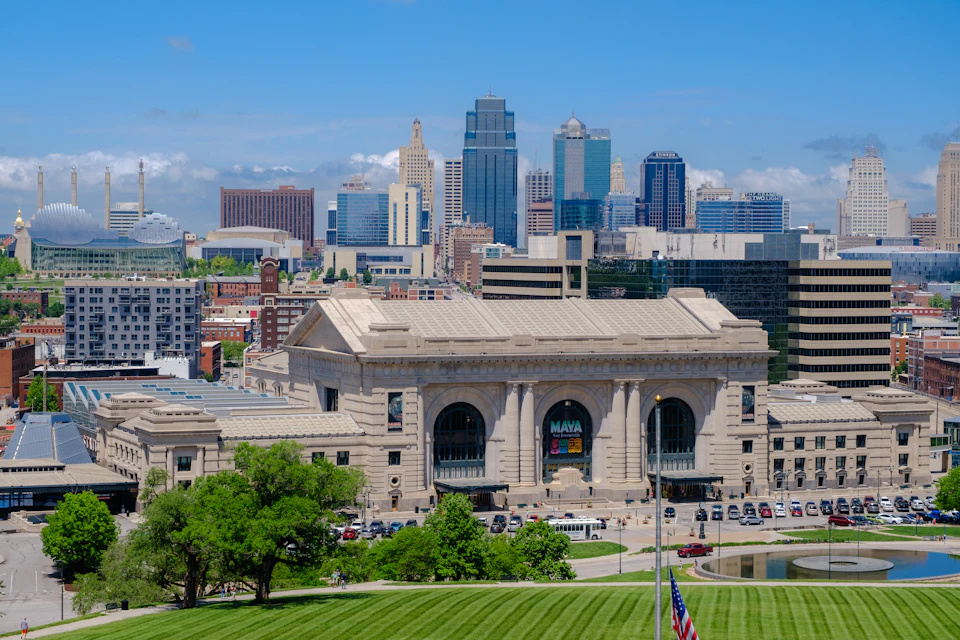
Finally, Missouri Car Insurance Built for Kansas City Drivers
Every day, Kansas City drivers navigate I-70 through downtown, merge onto I-35, take I-29 toward Kansas City International Airport, and deal with the stop-and-go of US-71/I-49. Add in traffic surges around Chiefs games at Arrowhead, Royals games at Kauffman, shopping runs to the Plaza and Brookside, and commuters crossing into Overland Park and Olathe for work – and the picture gets complicated fast.
On top of that, many drivers are frustrated by confusing coverage terms, unsure whether past tickets or a lapse in insurance policies will shut them out, and uncertain about whether Missouri or Kansas rules apply to their situation. It’s a lot to sort through alone.
MissouriAutoInsurance.com is a Missouri-focused agency that understands Kansas City specifically. We guide both good drivers with a clean driving record and drivers dealing with incidents, violations, or SR-22 requirements. Our goal is to help you meet Missouri law, protect your car and budget, and avoid overpaying for coverage you may not need.
Why MissouriAutoInsurance.com Works for Kansas City, MO Car Insurance
Most insurance in Kansas City advertising is generic – swap the city name and the page looks identical. We take a different approach, built around Missouri-specific expertise and the unique risks Kansas City drivers actually face, from urban traffic congestion to severe hail seasons.
Core Benefits for Kansas City Drivers
-
Missouri-Focused Guidance – We specialize in Missouri auto insurance requirements, including Kansas City’s local context: urban density, commuter corridors like I-70 and I-35, and the parking challenges that come with living in neighborhoods like Midtown and downtown KC.
-
Help for All Driving Histories – We regularly assist good drivers alongside those dealing with tickets, at-fault accidents, DUIs, or coverage gaps. If you need an SR-22 filing to reinstate your license, we can help arrange that too.
-
Clear Explanations of Coverages – We provide plain-English breakdowns of liability coverage (25/50/25), required uninsured motorist coverage (25/50), and optional comprehensive and collision – so you understand what you’re buying and why.
-
Flexible Options for City Life – We offer solutions for households with multiple drivers, rideshare commuters, students at UMKC or Rockhurst, and people parking on-street in Midtown or downtown where theft and weather exposure are real concerns.
-
Easy Online Start – Drivers can start quotes anytime at our online quote page and finish details with friendly follow-up from an agent, without needing an in-person office visit.
How Getting Kansas City, Missouri Car Insurance Works
The process is straightforward, even if you commute between Kansas and Missouri every day. Here’s how it works from quote request to active Missouri auto policy.
Step 1: Share Your Kansas City Driver and Vehicle Details
Start by visiting our Missouri car insurance quotes page. The form collects the address where each vehicle is garaged – this must be the Missouri address where the car is kept most nights, not a Kansas workplace.
Be prepared to provide:
-
Full legal names, dates of birth, and license numbers for all household drivers
-
Vehicle identification numbers (VINs), year, make, and model for each car
-
Lienholder or lease company information for financed vehicles
-
Any recent tickets, at-fault accidents, or license suspensions
Disclose all licensed household members. The insurer will explain how each driver must be rated, listed or otherwise handled under its rules. Being upfront about your full household and driving history leads to more accurate quotes and fewer surprises at claim time.
Step 2: Build a Policy That Fits Kansas City Roads and Your Budget
Once we have your details, an agent helps you choose liability limits, uninsured motorist limits, deductibles, and optional protections based on where and how you actually drive in KC.
Different coverage types respond to different real-life scenarios:
-
A rain-slick pileup on I-70 during rush hour – collision coverage helps pay for repairs to your own vehicle
-
A hit-and-run at an intersection on Troost – uninsured motorist bodily injury covers your medical costs, while collision coverage handles your car’s repairs
-
Hailstorm damage near the Plaza during a May thunderstorm – comprehensive coverage pays to fix dents and broken glass
-
Theft from Westport street parking – comprehensive coverage covers the loss
We’ll explain the trade-offs among different coverage services, higher liability coverage limits, adding comprehensive and collision, and adjusting deductibles so you can stay within budget while still protecting your assets.
Step 3: Finalize Your Missouri Policy and Get Proof of Insurance
Once coverage details are agreed upon, the agent issues a Missouri auto policy (subject to underwriting) and provides electronic ID cards. Kansas City drivers can show electronic insurance cards if stopped – Missouri allows electronic proof of insurance, which can be presented to Kansas City Police Department officers during traffic stops.
Proof of insurance may also be needed when you register a vehicle at a Missouri license office. You can locate nearby offices through the Missouri Department of Revenue website.
What Makes Our Kansas City, MO Car Insurance Approach Different
Searching for “cheapest car insurance” online returns dozens of nearly identical pages. We focus on outcomes and education instead of generic advertising.
Key Differences for Kansas City Drivers
-
Local Context, Not One-Size-Fits-All – We factor in city driving on the Downtown Loop, airport trips on I-29, tailgating traffic near the Truman Sports Complex, and the reality of cross-river commuting – because your right coverage depends on how you actually use your car.
-
Help With Complex Situations – We assist with Missouri SR-22 filings, non-owner SR-22 insurance for drivers without a car, and lapses after cancellations, using information aligned with Missouri DOR reinstatement resources.
-
Transparent Options for Affordable Coverage – We help find lower-cost coverage options without hiding that minimum coverage has real limits. Visit our cheap car insurance page for more on finding the right policy at the coverage and cost tradeoffs.
Understanding Kansas City, Missouri Minimum Car Insurance Requirements
Missouri requires minimum liability coverage for drivers. These rules apply regardless of which part of Kansas City you live in, as long as your car is garaged in Missouri. The figures below reflect Missouri DOR insurance requirements – we encourage you to verify current amounts there.
Missouri Liability Coverage: 25/50/25 Explained
Liability coverage is required by law in Kansas City. It includes bodily injury and property damage liability at these minimum levels:
-
$25,000 per person for bodily injury in a single accident
-
$50,000 per accident total bodily injury when multiple people are hurt
-
$25,000 per accident for property damage
To put this in a Kansas City context: imagine a multi-car accident on I-35 during morning rush. If you’re at fault and two passengers in the other vehicle need emergency care, their combined medical bills could easily exceed $50,000. Or picture hitting a parked car in Westport and damaging a storefront – $25,000 in property damage can be used up quickly.
Costs above these coverage limits can become your personal responsibility. Compare quotes at minimum and higher limits to see the actual price difference and extra protection. For more detail, see our minimum car insurance guide.
Required Uninsured Motorist (UM) Bodily Injury: 25/50
Missouri law also requires uninsured motorist bodily injury coverage at a minimum of $25,000 per person and $50,000 per accident. The required coverage applies throughout Missouri.
This coverage helps protect you and your passengers when an uninsured or hit-and-run driver causes injuries. For example, if someone runs a red light at a busy midtown Kansas City intersection and flees the scene, your UM bodily injury coverage can help pay for your medical treatment.
However, UM in Missouri typically covers medical and injury costs – not repairs to your own vehicle. Repairing your car after an uninsured driver crash normally requires collision coverage or paying out of pocket. Underinsured motorist coverage is not required in Missouri, though it’s available as an option.
Beyond the Minimum: Coverages Kansas City Drivers Commonly Choose
Many Kansas City drivers select higher limits and additional coverages because of urban traffic, severe weather, and the value of their vehicles. Here’s what those options look like in practice.
Higher Liability Limits
Drivers commuting daily on busy interstates or regularly carrying passengers – carpools, youth sports groups, family – often consider limits well above 25/50/25. Common options include 50/100/50 or 100/300/100. Higher limits cost more in premiums but can save money in the long run by shielding personal assets from a serious at-fault accident.
Collision Coverage for Your Car
Collision coverage is optional but protects your vehicle in accidents. It pays to repair or replace your car after an at-fault crash or collision with another vehicle or object – whether you slide into a guardrail on an icy stretch of I-29 in January or rear-end a car in stop-and-go traffic near the Plaza.
Selecting a higher deductible can lower monthly premiums but increases out-of-pocket costs after a claim. Finding the right balance between affordability and what you can pay if something happens is a conversation we have with every client.
Comprehensive Coverage for Theft, Weather, and Other Damage
Comprehensive coverage is optional and covers non-collision damages: theft, vandalism, hail, falling trees, fire, and certain animal strikes.
Comprehensive coverage may help with covered hail, theft, vandalism and other non-collision losses. Consider where you park and what deductible you could pay after a loss. A neighborhood or local weather description cannot predict your premium or guarantee a claim outcome.
If your vehicle is financed or leased, your lender almost certainly requires both comprehensive and collision coverage.
Uninsured and Underinsured Motorist Options
You can ask about higher UM bodily injury limits and optional underinsured motorist coverage. UM and UIM address different situations, and policy terms determine how benefits apply. Neither substitutes for physical damage coverage on your car.
Other Helpful Protections for Kansas City Drivers
Additional coverages worth discussing with your agent include:
-
Medical payments coverage – helps pay medical bills for you and passengers regardless of fault
-
Rental reimbursement – covers a rental car while yours is being repaired after a covered claim, useful if hail damage sends your vehicle to a shop for weeks
-
Roadside assistance – helpful for breakdowns on I-70, flat tires, or lockouts anywhere in the metro
-
Motorcycle insurance – worth discussing if you need protection for a motorcycle kept or used in Kansas City
These are optional add-ons, and your agent can review which ones make sense for your situation, including whether bundling separate policies may be appropriate for other vehicles.
Special Situations: SR-22 and Non-Owner Insurance in Kansas City, MO
Some Kansas City drivers need to file an SR-22 with Missouri DOR to reinstate or maintain their driving privilege. Our agency can help navigate that process. Specific rules and filing duration come from Missouri DOR and the DOR reinstatement requirements page – we recommend confirming details there or in your reinstatement letter.
When Missouri May Require an SR-22
Missouri may require proof of financial responsibility through an SR-22 filing after certain alcohol-related offenses, serious traffic violations, driving without insurance, or involvement in an uninsured accident. The DOR decides when an SR-22 is needed and for how long – duration can vary depending on the specific cause and whether it’s a first or subsequent offense.
Owner SR-22 Policies for Kansas City Drivers With a Car
An owner SR-22 policy is standard liability coverage (plus any optional coverages you choose) on a specific vehicle, with the insurer filing the SR-22 certificate on your behalf. Your policy must meet at least Missouri’s minimum liability limits and remain active for the entire required period. Any lapse can trigger a new suspension. Visit our SR-22 insurance page for a deeper overview.
Non-Owner SR-22 for Drivers Without a Car
Non-owner SR-22 insurance provides liability coverage for drivers who do not own a vehicle and do not have regular access to a household car. It satisfies the SR-22 filing requirement while you drive borrowed vehicles. Limitations apply: it typically does not include comprehensive or collision on any car and usually does not cover vehicles you own or regularly use. Learn more on our non-owner SR-22 insurance page.
Kansas City Driving Realities That Can Affect Your Coverage Choices
Local conditions in Kansas City directly influence which coverage options make sense. While we cannot promise specific car insurance rates for any particular road or neighborhood, understanding these factors helps you make smarter decisions.
For traffic safety information, the Kansas City Police Department is an official local resource. For emergency response context, the Kansas City Fire Department provides official fire-safety and emergency-response information.
Traffic Patterns and Major Roads
Kansas City sits at the crossroads of I-70, I-35, I-29, US-71/I-49, and the I-435 loop. These corridors see heavy commuter flow, with congestion intensifying during rush hours and around sporting events at Arrowhead and Kauffman stadiums. Frequent highway driving and stop-and-go conditions increase the potential severity of crashes, which influences decisions about liability limits and physical damage coverage.
Weather, Hail, and Storm Risk
Kansas City’s storm exposure is well documented. Comprehensive coverage and glass protection may be especially valuable here. Consider a scenario where a May thunderstorm drops golf-ball-sized hail across residential streets in Midtown – vehicles parked outside can sustain thousands of dollars in damage in minutes. Insurance companies use complex actuarial models to assess risk and determine premiums, and Kansas City’s weather history is part of that calculation.
Cross-State Commuting Between Kansas and Missouri
Your state of residence and where the vehicle is garaged – Missouri versus Kansas – control which state’s insurance requirements apply. Kansas City residents who live in Missouri but work in Overland Park or Olathe still carry Missouri-compliant policies. We can help structure coverage for cross-state use.
Never misstate your garaging address to try to affect price. Doing so can create claim denials and compliance problems that cost far more than any premium difference.
Who Our Kansas City, Missouri Auto Insurance Is For
We work with a wide range of Kansas City drivers – not just those with perfect records and new cars.
Drivers and Households We Commonly Help
-
Everyday commuters on I-70, I-35, I-29, and US-71 who need dependable liability, comprehensive, and collision coverage
-
City residents in downtown, Midtown, Westport, the Northland, and South Kansas City who park on-street or in shared garages and worry about theft, vandalism, and weather damage
-
Students and young drivers attending UMKC, Rockhurst, and other area schools who may be new to Missouri insurance rules or sharing vehicles with family – age and driving experience significantly influence car insurance premiums
-
Drivers with tickets, at-fault accidents, or prior lapses who need to get legal again under Missouri law, including those who may need SR-22 filings
-
Missouri residents commuting daily into Kansas suburbs who want one clear Missouri auto policy that fits their cross-border driving
What Can Affect Your Car Insurance Price in Kansas City, Missouri
Your driving history, vehicle, coverage choices, garaging address and other rating factors affect your quote. Compare actual offers using the same limits and deductibles; a citywide average cannot predict your price.
Common Rating Factors
-
Driving history – Tickets, at-fault accidents, and serious violations like DUIs typically increase costs. A clean driving record typically qualifies drivers for lower insurance premiums.
-
Coverage choices – Higher coverage limits and adding comprehensive or collision increase premiums but offer stronger protection. Higher deductibles reduce premiums but raise out-of-pocket risk.
-
Vehicle type and usage – Age, value, safety features, and whether the car is used for commuting, pleasure, or business (like rideshare) all matter.
-
Garaging and mileage – Living and garaging in urban Kansas City versus other parts of Missouri can influence pricing, but we cannot guarantee how any one ZIP code will rate.
-
Credit-based scores – Missouri allows insurers to use credit-based insurance scores to help determine pricing. Maintaining good credit may work in your favor.
-
Household factors – Number of drivers, prior insurance continuity, and any required filings such as SR-22 all factor into what you pay.
Major factors influencing car insurance rates include driving history, coverage level, and local risks – and Kansas City has a unique combination of all three.
How to Save on Kansas City, Missouri Car Insurance Without Cutting Needed Protection
Dropping to bare-minimum coverage isn’t the only easy way to save money. Smart strategies can lower your cost without leaving you exposed.
Practical Ways Kansas City Drivers May Reduce Costs
-
Review coverage and deductibles annually – As vehicles depreciate, it may make sense to adjust comprehensive or collision coverage or raise deductibles.
-
Ask about discounts – Safe driver discounts can lower your insurance premium. Kansas City drivers can save with anti-theft device discounts, and good student discounts are available for teen drivers. Multi-policy discounts can reduce overall insurance costs as well.
-
Bundle policies – Kansas City drivers can save by bundling insurance policies. Bundling home and auto insurance can save money, and even renters coverage bundled with auto may qualify for a discount.
-
Maintain continuous coverage – Gaps in insurance history can make future policies more expensive. Keeping your auto policy active, even during periods of low driving, protects your rate history.
-
Comparing quotes from multiple providers can save money – Shopping around and comparing quotes can help drivers find competitive rates and take advantage of available discounts to improve affordability. Visit our cheap car insurance page for more ideas on finding affordable coverage.
-
Keep driving records clean – Follow traffic laws and stay aware of local enforcement and safety resources. A clean record may improve your insurance options over time.
Kansas City, Missouri Car Insurance Checklist: What to Have Ready for a Quote
Having your details ready helps the agent prepare an accurate comparison. Start with your contact details, then supply household and vehicle information. A request is not an instant rate or binding coverage.
Your Kansas City Quote Preparation List
-
Full legal names, dates of birth, and license numbers for all household drivers, including adult children living at home
-
Home address where each vehicle is primarily garaged in Kansas City, Missouri (or elsewhere in Missouri, if applicable)
-
Vehicle details: year, make, model, approximate mileage, and VIN if available
-
Current or most recent auto insurance information (if any), including liability limits and expiration date
-
List of any tickets, at-fault accidents, or major violations in the last several years, with approximate dates
-
Loan or lease information for each financed vehicle, so we can help meet lender coverage requirements
-
Any letters or notices from Missouri DOR about suspensions, revocations, or SR-22 requirements
Once you’ve gathered these items, request your Kansas City quote here.
Frequently Asked Questions About Kansas City, Missouri Car Insurance
These are common questions Kansas City drivers ask about Missouri coverage, cross-state commuting, and SR-22 filings.
Do I need a Missouri policy if I live in Kansas City, Missouri but work in Kansas?
Your insurance should be written for the state where the vehicle is garaged and where you are a legal resident. If that is Kansas City, Missouri, you need a Missouri-compliant policy. Driving into Kansas for work or errands is normally fine with a Missouri policy, but your residency and garaging address must be accurate.
Does Missouri’s uninsured motorist coverage repair my car after a hit-and-run in Kansas City?
Required Missouri UM coverage is for bodily injury only – it does not cover damage to your vehicle. Repairing your car usually requires collision coverage or paying out of pocket, even if the other driver is uninsured or flees the scene.
How do I know if I need an SR-22 in Missouri?
Missouri DOR notifies drivers when an SR-22 is required, typically through a reinstatement letter or suspension notice. Review your DOR paperwork and visit the official Missouri DOR pages for current rules. Contact us if you need help arranging a filing.
Can I get Kansas City car insurance if I had a lapse in coverage?
Many drivers with lapses can still find coverage, though pricing and options may differ from continuously insured drivers. Be upfront about your history so we can help you restart legal coverage as efficiently as possible.
Will my Kansas City neighborhood automatically raise or lower my rate?
Insurers may consider territory or ZIP code among many rating factors, but we cannot promise that any specific neighborhood will be rated higher or lower. The best way to see your actual price is to request a personalized quote with accurate garaging information.
Get Started on Your Kansas City, Missouri Car Insurance Quote
If you’re ready to stop guessing about your coverage options and start finding the right policy for your life in Kansas City, the next step is simple.
MissouriAutoInsurance.com helps Kansas City drivers understand their options, follow Missouri law, and choose coverage that fits the way they actually drive in this metro. Whether you need basic liability, full comprehensive and collision, or an SR-22 filing, the team at Drivers Insurance Agency, Inc. are here to help.
Request your Kansas City, MO car insurance quote now – submitting your information requests assistance and does not bind coverage or guarantee acceptance.
Exploring more?
-
Missouri car insurance quotes – statewide quote information
-
Other Missouri city guides – coverage guides for cities across the state
-
Independence car insurance – for nearby Independence drivers
-
Lee’s Summit car insurance – for Lee’s Summit drivers
-
Liberty car insurance – for Liberty drivers
Official Driver Licensing Resources
Use the Missouri DOR license-office locator to confirm current locations, services and hours before visiting. Driver testing and license-office services can be handled by different agencies. For an emergency, call 911; use official agency guidance for non-emergency reporting.
Coverage examples are illustrative. Actual benefits depend on a covered loss, policy limits, deductibles and exclusions.