On this page
Columbia Missouri Car Insurance Made Simple For Local Drivers
Columbia combines university-area parking, family households and regional highway commuting. Students at the University of Missouri, Columbia College and Stephens College may share vehicles or keep them away from a permanent home address, making accurate driver and garaging information particularly useful.
Whether you’re navigating I‑70 during rush hour, hunting for a parking spot near Faurot Field, or trying to figure out how Missouri insurance rules apply to an out-of-state student car, this page breaks down what Columbia drivers actually need to know. MissouriAutoInsurance.com, operated by Drivers Insurance Agency, Inc., helps local customers understand their coverage options and compare quotes from multiple insurers – without jargon, pressure, or government affiliation.
Ready to see what’s available? You can start a quote at any time. Submitting a quote request begins the process but does not bind coverage or guarantee acceptance.
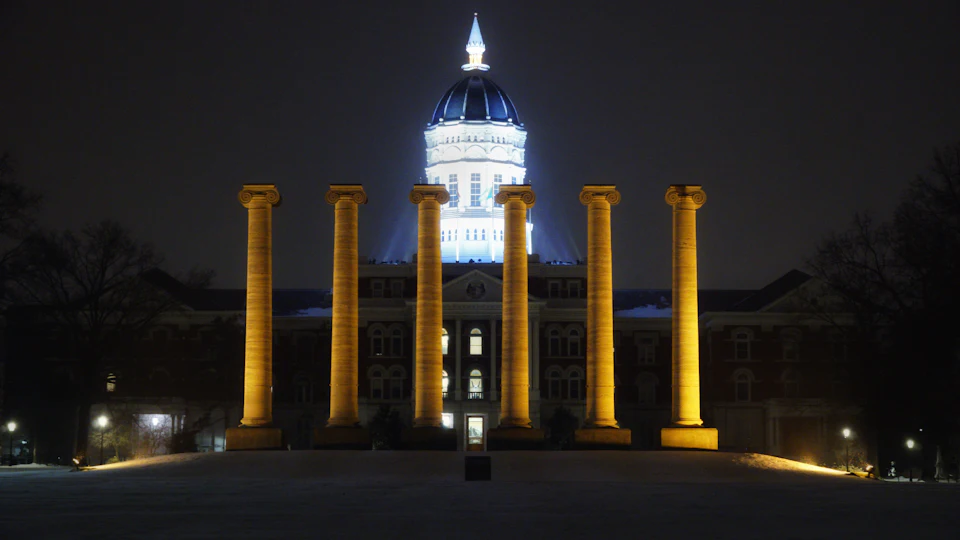
Finally, A Columbia Car Insurance Resource Built For Missouri Drivers
Most drivers in Columbia, MO know they need car insurance, but sorting out what coverage to choose, what the state actually requires, and how local factors like campus parking or highway commuting affect their options can feel overwhelming. Rates for car insurance can vary significantly between different insurance providers, and insurance costs can be influenced by factors like vehicle type and driving history in Columbia, Missouri. Without clear guidance, it’s easy to overpay – or worse, carry too little protection.
MissouriAutoInsurance.com, operated by Drivers Insurance Agency, Inc., helps drivers compare available insurance options and understand the coverage terms. This guide focuses on Missouri requirements and practical Columbia-area situations without promising a particular price or acceptance.
Common Columbia, MO Car Insurance Headaches
Columbia drivers and Boone County residents deal with insurance frustrations that are specific to this area:
-
New to Columbia – Mizzou, Columbia College, and Stephens College students and staff arriving from out of state and unsure how Missouri insurance rules apply to their vehicles.
-
Busy, high-traffic routes – Worry about driving on I‑70, Stadium Boulevard, Providence Road, Broadway, and US‑63, where traffic volumes are heavy and conditions change with the weather.
-
Coverage confusion – Unsure how much more than the Missouri minimum coverage is truly needed, especially when balancing a tight budget against real risk.
-
Record issues – Tickets, accidents, or coverage lapses on record, with confusion about SR‑22 filings or license reinstatement steps.
-
Parking exposure – Parking on or near campus in open lots or on downtown streets, with concerns about theft, vandalism, or storm damage.
-
Budget pressure – Trying to find affordable protection without sacrificing the coverage that matters most.
Why MissouriAutoInsurance.com Works For Columbia Drivers
This section explains how MissouriAutoInsurance.com addresses those specific Columbia and Boone County headaches – not with generic promises, but with practical, Missouri-focused help.
Key Benefits For Drivers In Columbia And Boone County
-
Missouri‑Specific Expertise – Our focus is entirely on Missouri insurance rules and Columbia-area realities. We help you understand the state’s required 25/50/25 liability minimums and mandatory uninsured motorist bodily injury coverage so you know exactly where you stand before choosing additional protection.
-
Guidance For Campus And City Parking – Independent agents help you think through whether comprehensive coverage makes sense based on where you park. If your car sits overnight in an open lot near campus or on a downtown street, the risk profile is different than a secured garage – and we help you weigh those details.
-
Support For Good And High‑Risk Drivers – Whether you have a clean record or you’re dealing with tickets, accidents, or a lapse in coverage, we help you review options. Independent agents help you avoid overpaying for insurance by finding the right fit for your situation.
-
Plain‑English Explanations – We break down terms like liability, collision, comprehensive, deductibles, and SR‑22 so you can make decisions with confidence rather than confusion. Independent agents simplify the insurance process by handling details for you.
-
Flexible Coverage Discussions – From daily commuters on I‑70 and US‑63 to occasional drivers who mostly walk around downtown, we consider how you actually use your vehicle. We help households compare available ways to insure their actual drivers and vehicles.
-
Online Convenience With Local Insight – The quote process starts online via the quote page, backed by Drivers Insurance Agency, Inc., a agency serving Missouri drivers. You get digital ease with the benefit of a real person reviewing your details.
How Columbia Missouri Car Insurance Works
Understanding your coverage starts with knowing what Missouri law requires, then building on that foundation based on how and where you drive in Columbia. Legal requirements are set by the Missouri Department of Revenue (DOR), not by any city or insurance company. Here’s how the process works.
Step 1: Understand Missouri’s Required Minimum Car Insurance
Every Columbia driver must meet the same statewide requirements, regardless of neighborhood, campus status, or employer. Missouri requires liability insurance for all drivers, with minimums of:
-
$25,000 bodily injury liability per person
-
$50,000 bodily injury liability per accident
-
$25,000 property damage liability per accident
This is commonly written as 25/50/25. Bodily injury liability in Missouri is $25,000 per person and $50,000 per accident, while property damage liability in Missouri is $25,000 per accident.
Missouri also requires uninsured motorist (UM) bodily injury coverage at minimum limits of $25,000 per person and $50,000 per accident. Uninsured motorist coverage is available for added protection against injuries when the at-fault driver has no insurance. However, UM bodily injury coverage does not pay to repair or replace your own vehicle – that requires collision or comprehensive coverage.
To register or renew a vehicle, you must show proof of insurance. Failing to maintain required coverage can result in suspension of your driver license and registration, with reinstatement fees that escalate with repeat offenses. The DOR’s insurance requirements page explains these rules in detail.
These are minimum legal requirements – not necessarily recommended coverage levels for every driver.
Step 2: Choose Coverage That Fits Columbia‑Area Driving
After meeting the legal minimums, Columbia drivers decide whether to add more protection based on driving habits, vehicle value, and personal risk tolerance. Here are the key coverage choices:
-
Higher Liability Limits – Many Columbia households consider limits above 25/50/25, especially if they commute daily, own a home, or have savings to protect. A serious crash on a busy route like I‑70 or North Providence Road could produce costs well beyond the state minimums. Higher limits provide a larger financial buffer.
-
Collision Coverage – Collision coverage pays for vehicle damage after an accident, regardless of who is at fault, subject to your deductible and policy terms. In Columbia, frequent stop-and-go near campus, parking lots around The District and Columbia Mall, and heavy football-game traffic near Faurot Field all increase exposure to fender benders and lot collisions. Lenders and leasing companies typically require collision and comprehensive coverage for financed or leased vehicles; these coverages are not Missouri’s state-mandated minimum insurance.
-
Comprehensive Coverage – May help with covered theft, vandalism, hail, falling objects and other non-collision losses. Disclose your actual parking arrangement and ask how your deductible applies. Personal belongings inside a car generally need separate coverage.
-
Deductibles – Your deductible is the amount you pay out of pocket before insurance covers the rest on a collision or comprehensive claim. Higher deductibles generally lower premiums but increase your financial burden after a loss. Choose a deductible you could realistically pay after an accident or storm.
-
Medical Payments Or Other Optional Protections – Medical payments coverage can help with medical bills after a crash regardless of fault, where available and subject to policy terms. Telematics programs offer potential savings for safe driving habits through some insurers. Options vary by insurance company; we help explain typical choices when quoting.
Coverage decisions are personal. The right answer depends on your driving habits, budget, and how much risk you’re comfortable carrying.
Step 3: Get Insurance Company Quotes Built Around Your Columbia Driving Habits
Getting a clear quote is the final step after understanding your needs:
-
Visit the online quote form and answer questions about your vehicles, drivers, Columbia address, and driving history.
-
Our agency reviews your details and helps explain coverage options available from the companies we work with.
-
You decide what works – there is no obligation to buy, and submitting a quote form does not instantly bind coverage.
Local factors like garaging within Columbia city limits versus outside, daily mileage from home to campus or work, and vehicle type all play a role in pricing and coverage options. It is advisable to regularly compare insurance quotes to secure better rates. Comparing rates from multiple insurers can help find competitive pricing for car insurance in Missouri. If you’re moving between Missouri cities, you can also compare this guide with our statewide overview.
What Makes MissouriAutoInsurance.com Different For Columbia, MO
Other resources talk about insurance in general. We focus on outcomes for Columbia drivers – practical guidance that reflects where you actually live and drive.
Local Insight, Missouri Focus
Tell the agent how you use I-70, US-63, Stadium Boulevard, Broadway and Providence Road, along with your annual mileage and overnight parking address. Daily campus trips and a regular Columbia-to-Jefferson City commute can involve different vehicle-use details, even though the same Missouri minimums apply.
If you’re comparing coverage in other parts of the state, check our pages for Jefferson City car insurance, Wentzville car insurance, or browse all Missouri cities.
Support For Students, Families, And Commuters
Columbia’s driving population includes distinct groups, each with different needs:
-
University of Missouri, Columbia College, and Stephens College students who bring vehicles from out of state and need to comply with Missouri registration and insurance rules.
-
Faculty, staff, and medical professionals driving to MU Health Care and other major employers across the city.
-
Families in neighborhoods across Boone County who share multiple vehicles and want to protect every driver in the household.
Being a student does not change Missouri’s minimum requirements, but students often have unique parking and budgeting concerns. Some insurers offer student discounts with their own eligibility rules – though availability depends on the insurance company, and we cannot promise any specific discount. We help students understand how to list drivers, garaging addresses, and usage correctly so their quotes are accurate.
Clear Guidance On High‑Risk Situations And SR‑22
Some drivers need an SR-22 filing as specified by their Missouri DOR reinstatement requirements; a high-risk rating alone does not establish that requirement. MissouriAutoInsurance.com includes dedicated resources for SR‑22 insurance and non‑owner SR‑22 insurance.
The Missouri DOR – not our agency – sets SR‑22 and reinstatement rules, with official details at the reinstatement requirements page. There is no single universal “three‑year rule” for SR‑22 in Missouri; the required filing period depends on the specific offense and your DOR notice. For example, suspensions due to an accident judgment may require SR‑22 for two years, while suspensions for false insurance or mandatory insurance violations may require three years. We help drivers understand what an SR‑22 filing is and how it works with a policy, but we cannot change the DOR’s timelines or fees.
Who Columbia Missouri Car Insurance Guidance Is For
This page was built for the people who actually drive and park in Columbia and Boone County:
-
Columbia Commuters – People driving daily on I‑70, US‑63, or between north Columbia and campus or medical centers who want coverage that matches their highway exposure.
-
University And College Students – In-state and out-of-state students bringing cars to Mizzou, Columbia College, or Stephens who need help understanding Missouri insurance rules and choosing appropriate protection.
-
Boone County Families – Households in Columbia and surrounding communities who want to protect multiple vehicles and drivers. Ask how adding a driver to an eligible household policy compares with other available arrangements.
-
Drivers With Tickets, Accidents, Or Lapses – Anyone needing guidance on getting back on the road legally after license issues, suspensions, or coverage gaps.
-
Car Owners And Occasional Drivers – From daily commuters to people who mostly walk or bike around downtown but keep a car for weekend trips and want the right level of protection.
Columbia‑Specific Driving And Parking Considerations
Local geography, roads, and parking shape how Columbia drivers think about coverage – even though they don’t change the legal minimums.
Commuting On I‑70, US‑63, And Major Columbia Roads
Columbia drivers rely on several major routes daily:
-
Interstate 70 runs east–west across the north side of the city, connecting Columbia to Kansas City and St. Louis.
-
US‑63 runs north–south, linking Columbia to Jefferson City and other Mid-Missouri towns.
-
Key city arterials include Stadium Boulevard, Providence Road, Broadway, Nifong Boulevard, and the Business Loop 70 corridor.
Frequent highway use may influence how much liability and collision protection a driver wants. Commuters putting on higher mileage should share accurate annual mileage estimates during quoting. Avoid assuming any neighborhood is automatically “safer” or “riskier” for pricing purposes – insurers use many factors, not just a single street name.
Campus And Downtown Parking Near The University Of Missouri
Parking situations in Columbia vary widely:
-
Campus parking can involve garages, surface lots and permitted spaces. Check current university parking rules and disclose where your vehicle is normally kept during the school term.
-
The District and downtown Columbia feature street and lot parking near bars, restaurants, and apartments.
-
Off-campus student housing complexes often have large, unsheltered open lots.
Comprehensive coverage can help with theft, vandalism, and some storm damage for vehicles parked in exposed locations, subject to deductible and policy terms. Drivers should be honest about where the car is primarily kept – the garaging address – when requesting quotes. Misrepresenting where a vehicle is stored can lead to denied claims or policy issues. Check university parking rules and city parking regulations as well, since policy conditions may apply if vehicles are used or stored differently than stated.
Weather, Seasons, And Mid‑Missouri Driving Conditions
Columbia’s Midwest continental climate creates year-round risk:
-
Summer thunderstorms can bring hail and wind. Comprehensive may help with covered damage to a parked car, subject to policy terms and the deductible.
-
Winter snow and ice can make roads slippery. Collision is the relevant vehicle coverage for a covered crash on ice; comprehensive addresses different types of loss.
-
Spring and fall storms can bring high winds, lightning, falling tree limbs, and localized flooding in low-lying areas.
Comprehensive coverage is often considered by drivers concerned about hail or falling limbs. Collision coverage matters for those worried about weather-related crashes on icy roads. Factor in seasonal conditions when thinking about deductibles and whether roadside assistance or towing options make sense.
Understanding SR‑22 And Non‑Owner Policies In Columbia
Some Columbia drivers are dealing with license suspensions, revocations, or situations where they no longer own a vehicle but still need to drive legally. Detailed resources are available for SR‑22 insurance and non‑owner SR‑22 insurance.
SR‑22 Filings With The Missouri DOR
An SR‑22 is a form filed by an insurance company with the Missouri DOR proving the driver carries at least the required liability insurance. It is not a type of coverage – it is a certification attached to a policy.
Use your DOR notice and the official reinstatement requirements to determine the exact filing and period. For mandatory insurance suspensions, DOR lists reinstatement fees of $20, $200 or $400 depending on the suspension history. Other reinstatement categories have different requirements and fees.
Our agency cannot waive DOR fees or requirements but can help arrange a policy that includes an SR‑22 filing when needed.
Non‑Owner Insurance And Regular‑Use Limitations
Non‑owner car insurance provides liability coverage for people who do not own a vehicle but drive cars they do not own on an occasional basis. This can be relevant for some students, downtown residents, or people borrowing or using employer vehicles – subject to eligibility.
Typical limitations include:
-
Policies are generally not designed for someone who has regular access to a specific car in their household – for example, a partner’s car they use every day.
-
Insurers may decline non‑owner policies if the driver owns a vehicle or has one available for regular use.
Fully disclosing living arrangements and vehicle access when requesting non‑owner coverage is essential. Misrepresenting usage or ownership can lead to denied claims or non-renewal.
Pricing, Budgeting, And “Cheap” Columbia Car Insurance
Your Columbia quote depends on your driving record, vehicle, coverage selections, garaging address and insurer. Compare actual offers at matching limits; a generic monthly range cannot predict what you will pay.
For more on budget-friendly approaches, see our guides to minimum car insurance and cheap car insurance.
Finding A Policy That Fits Your Columbia Budget
-
State Minimum‑Focused Plan – Built around Missouri’s 25/50/25 liability plus required UM bodily injury 25/50. This meets legal requirements but may not provide enough protection after a serious crash, especially on high-traffic corridors like I‑70 or US‑63. Drivers in Missouri may opt for minimum liability instead of full coverage to lower costs for older vehicles.
-
Balanced Protection Plan – A middle-ground approach with liability above the minimums, plus collision and comprehensive on newer or financed vehicles. Many Columbia drivers who rely on their car for work or school lean toward this level because it covers both at-fault accidents and non-collision losses like theft or hail.
-
Expanded Coverage Plan – A more robust option for households with multiple vehicles, higher incomes, or more assets to protect. May include higher liability limits and extra protections like medical payments or rental reimbursement when available from participating insurers.
Actual rates depend on many factors: driving record, vehicles, garaging address, and more. A quote request is the first step in seeing what’s available. Coverage starts at the effective date and time confirmed by the insurer after its binding requirements are met.
Columbia Car Insurance Quote Checklist
Before you contact us for a quote, gather these details to make the process smoother:
-
Vehicle Information
-
Year, make, model, and VIN for each car to be insured
-
Current mileage and whether the vehicle is financed or leased
-
-
Driver Details
-
Full names, dates of birth, and driver’s license numbers for all household drivers
-
Driving history: recent tickets, accidents, suspensions, or SR‑22 requirements
-
-
Columbia‑Area Use And Parking
-
Approximate daily commute distance and main roads used (I‑70, US‑63, Stadium, Providence, etc.)
-
Typical parking location: campus garage, street parking, driveway, or apartment complex lot
-
-
Coverage Preferences
-
Whether you want just Missouri minimum liability or higher limits
-
Desired collision and comprehensive coverage and preferred deductibles
-
-
Current Policy (If Any)
-
Expiration date of existing policy to avoid coverage gaps
-
Current limits and deductibles for comparison
-
Once you have this information, visit https://missouriautoinsurance.com/quote/ to begin.
Official Columbia And Missouri Driving Resources
These independent resources help Columbia drivers stay informed. MissouriAutoInsurance.com is not affiliated with any of these agencies.
-
Missouri Department Of Revenue – Insurance Requirements – Explains statewide proof of financial responsibility and minimum insurance rules. URL: https://dor.mo.gov/driver-license/insurance/
-
Missouri Department Of Revenue – Revocation And Reinstatement Requirements – Lists official steps, fees, and timelines to reinstate a suspended or revoked Missouri driver license. URL: https://dor.mo.gov/driver-license/revocation-reinstatement/reinstatement-requirements.html
-
City Of Columbia Police Department – Local law enforcement information, traffic safety updates, crash reporting guidance, and annual crime reports. URL: https://www.como.gov/police/
-
Columbia Fire Department – Fire and emergency response information, safety resources, and contact info. URL: https://www.como.gov/fire/
-
City Of Columbia Transportation/Public Works – Updates on road projects, winter weather operations, and parking services that may affect daily driving. URL: https://www.como.gov/public-works/
Frequently Asked Questions About Columbia Missouri Car Insurance
These FAQs address the most common questions from Columbia and Boone County drivers.
Do Columbia Drivers Have Different Insurance Requirements From The Rest Of Missouri?
No. Columbia drivers follow the same statewide minimums: 25/50/25 liability plus UM bodily injury 25/50. Cities cannot lower state insurance requirements. Columbia may enforce local traffic and parking rules, but minimum coverage laws apply uniformly across Missouri.
How Does Being A Student At The University Of Missouri Affect My Car Insurance?
Being a student does not change state minimum requirements. However, students should use accurate garaging addresses – whether that’s a dorm, apartment, or parents’ home – when getting quotes. Out-of-state students who register vehicles in Missouri must meet Missouri insurance laws. Some insurers may offer their own rating factors or potential discounts (some insurers offer student discounts with their own eligibility rules), but availability varies by insurance company and is not guaranteed.
Is Uninsured Motorist Coverage Required In Columbia, MO?
Yes. Missouri requires uninsured motorist bodily injury coverage at minimum limits of 25/50 statewide. However, UM bodily injury coverage does not repair the policyholder’s own car. Collision and comprehensive coverage are needed for that type of protection, subject to policy terms.
Can I Get Car Insurance In Columbia If I Need An SR‑22?
Many insurers offer policies that can include an SR‑22 filing, but availability depends on the driver’s record and other underwriting factors. Review your DOR notice to confirm how long an SR‑22 is required, then request help via our SR‑22 insurance page. Rates may be higher after serious violations, but we do not quote exact increases on this page.
What If I Do Not Own A Car But Still Drive In Columbia?
Non‑owner car insurance provides liability coverage for people who do not own a vehicle but occasionally drive cars they do not own. This type of policy is generally not meant for drivers with a car in their household available for regular use. Visit our non‑owner SR‑22 insurance page for more detail and to see if this type of policy might apply to your situation.
How Do I Start A Columbia Car Insurance Quote With MissouriAutoInsurance.com?
Visit https://missouriautoinsurance.com/quote/. Complete the secure online form with accurate driver, vehicle, and coverage information. Wait for follow-up to review available options. Coverage starts at the effective date and time confirmed by the insurer after its binding requirements are met.
There is no obligation to buy and no government affiliation. Independent agents provide clear coverage explanations tailored to your needs and enjoy helping you find the right fit.
Get Started On Your Columbia Missouri Car Insurance Today
Understanding Missouri’s state minimums, choosing the right coverage for your situation, and considering local driving habits – from campus parking to I‑70 commutes – puts you in control of your protection and your budget. Whether you’re a Mizzou student parking in an open lot, a Boone County family with multiple drivers, or a commuter logging highway miles every day, the right policy starts with accurate information and honest guidance.
MissouriAutoInsurance.com helps good drivers and drivers with challenges – tickets, accidents, lapses, SR‑22 needs – explore options that match their needs. As independent agents, we shop multiple insurance companies so you can enjoy the ease of one-stop comparison with the confidence of clear coverage explanations.
Start your Columbia car insurance quote today. A quote request begins the process but does not bind coverage or guarantee acceptance. Your next step toward the right protection is just a few details away.
For current locations, services and hours, consult the Missouri DOR license-office locator.
Examples are illustrative. Coverage depends on policy terms, limits, deductibles and exclusions. A quote request does not bind coverage or guarantee acceptance.